Chapter 4 - THE NUMBER THAT WOULD NOT BALANCE
By the time I was medically cleared to walk three blocks without someone hovering beside me, Crestmont’s audit committee had hired an outside forensic accounting firm.
I was not allowed to participate directly.
That frustrated me.
I had spent eight years understanding the company’s inventory systems, and now strangers were tracing the discrepancy I found.
Rachel called that frustration a sign of life.
“Good. Be annoyed. Just do not interfere with an independent investigation.”
So I waited.
Waiting was harder than cardiac rehabilitation.
Three mornings a week, I walked on a treadmill while a nurse watched my rhythm.
I learned what my new heart rate felt like on beta blockers.
I learned not to touch the ICD incision every ten minutes.
I learned that survival had paperwork.
Medication schedules.
Device checks.
Insurance authorizations.
Work-leave forms.
At home, Sophie taped a note above my coffee maker.
YOU ARE NOT A SPREADSHEET.
I hated it enough to leave it there.
Nathan visited on a Sunday with a flash drive he did not give me.
“I can’t hand over company data,” he said immediately.
“Good.”
“I can tell you what I told the auditors.”
We sat on my balcony.
Chicago had turned cold.
Nathan explained the pattern.
The $4,187,920 variance was not missing inventory in one place.
It was duplicated value.
Shipments transferred between warehouses were being recorded as received at the destination without being properly relieved from the origin.
For a few days, both locations counted the same goods.
Normally the system corrected automatically.
But someone had been repeatedly applying M-77 overrides to prevent the originating location from clearing.
“Why?”
“Quarter-end inventory value.”
I understood.
Crestmont used certain inventory measures in debt covenants and acquisition models.
Inflated inventory could make working capital appear stronger.
“Was it Martin?”
Nathan rubbed his face.
“His credentials.”
“Credentials can be used by other people.”
“I know.”
“What about Northline?”
He looked at me.
“That is worse.”
Northline Recovery had been billing Crestmont for reconciliation services tied to the same warehouses experiencing the largest duplicate-value adjustments.
“Who approved the invoices?”
“Martin.”
“Who owns it?”
“We didn’t know at first.”
My stomach tightened.
Nathan looked toward the street.
“The registered agent has a home address. The house belongs to Martin’s sister.”
I said nothing.
“The LLC manager is her husband, Greg Hale.”
“Brother-in-law.”
“Yeah.”
The word fraud appeared in my mind.
I did not say it.
Nathan did.
“It looks like an undisclosed related-party vendor.”
“How much?”
“Six hundred forty-two thousand paid. Another one hundred eighty pending.”
I closed my eyes.
Martin had not simply wanted clean numbers.
He may have been getting paid for helping create the dirt.
Nathan continued.
“The auditors found emails.”
“What emails?”
“I don’t know everything.”
“Nathan.”
“I really don’t.”
He leaned forward.
“But one message says Northline’s fees would increase if the acquisition closed.”
The acquisition.
That explained pressure.
Bonus targets.
Vendor upside.
Inventory value.
The numbers were beginning to form a motive.
Still, none of it explained why Martin would tell people not to help me.
Fear could make people irrational.
Liability could make managers stupid.
But Daniel’s training certificate made simple ignorance impossible.
Rachel warned me not to overreach.
“Do not turn negligence into intent unless evidence supports it.”
“I know.”
“Say it.”
“Martin may have failed to help me for reasons we do not understand.”
“Good.”
I hated good legal language.
It refused emotional satisfaction.
That week, Crestmont finally let Rachel and me view the conference room footage under confidentiality.
No audio.
One fixed camera above the glass door.
I watched myself enter at 10:17.
Blue dress. Gray blazer. Laptop in my arms.
Alive.
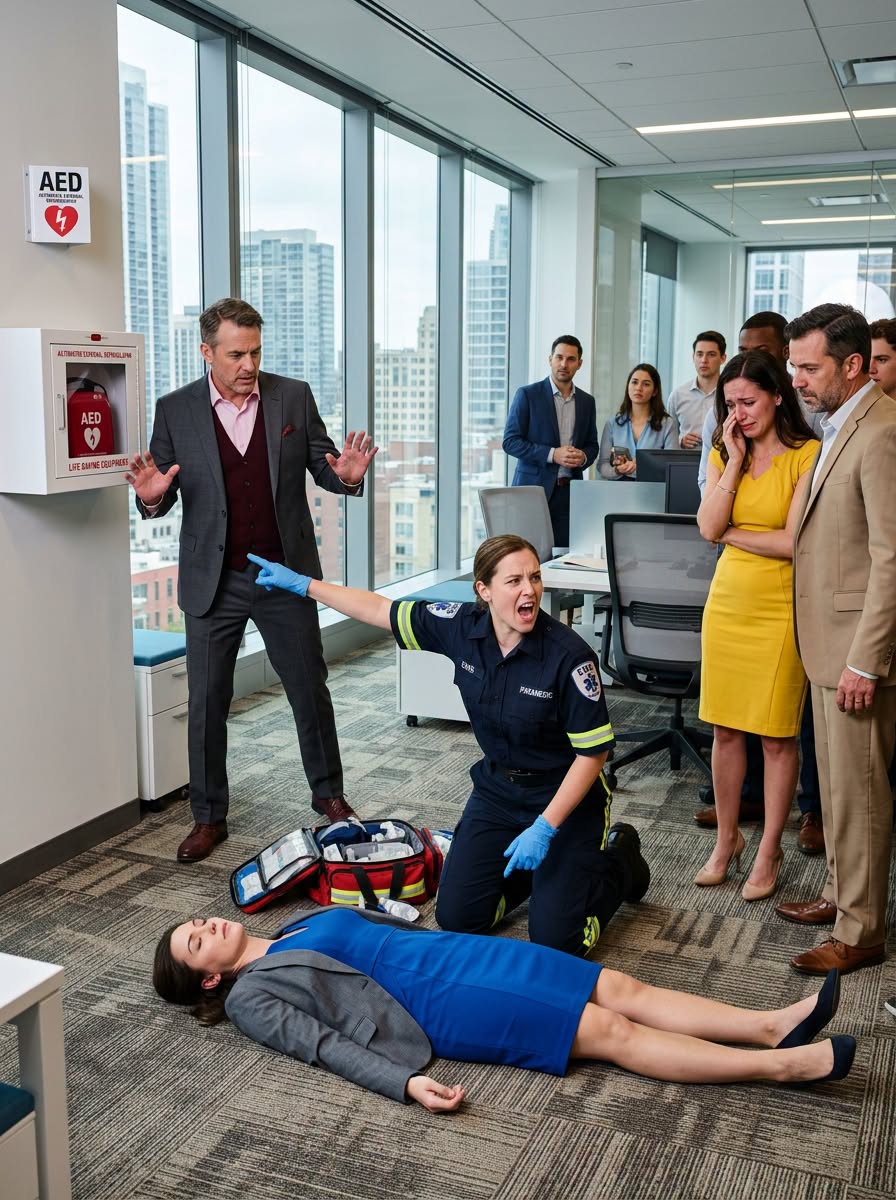
At 10:24:11, I reached for the chair.
At 10:24:14, I hit the floor.
Jenna stood immediately.
Martin raised one hand.
She sat.
At 10:24:36, Nathan moved around the table.
Martin stepped into his path.
They exchanged words.
At 10:24:58, Nathan crouched near me.
At 10:25:04, Martin touched his shoulder.
Nathan stood.
For nine seconds.
Then Jenna moved toward the door with her phone.
Martin pointed back toward the table.
At 10:25:31, Nathan dropped to his knees again.
He checked my neck.
At 10:25:39, he began compressions.
Eighty-five seconds.
Not three minutes.
Not nine.
Eighty-five seconds from collapse to CPR.
Less than witnesses feared.
More than emergency medicine wants.
The AED remained untouched.
At 10:26:02, Jenna called 911.
At 10:31:14, paramedics entered.
I watched the footage twice.
Then I asked Rachel to stop.
She did.
My hands were shaking.
“Eighty-five seconds,” I said.
“Yes.”
“That sounds small.”
“It is not nothing.”
“It also isn’t nine minutes.”
“No.”
Truth complicated anger.
Martin had delayed help.
He had not left me untouched for nine minutes.
Nathan’s CPR had been in progress for more than five minutes before EMS entered.
That mattered.
I felt relieved and furious at once.
Then the video continued in my mind.
Martin blocking Nathan.
Martin gesturing Jenna back.
He had not frozen.
He had acted.
Just in the wrong direction.
The outside investigators interviewed me the next day.
Three people on video.
One attorney.
One accountant.
One operational controls specialist.
They asked about M-77.
Northline.
Martin’s instructions.
The deleted slides.
The HR memo.
Near the end, the attorney asked, “Did Mr. Hale ever ask you to approve Northline invoices?”
“Yes. Twice.”
“Did you?”
“The first time. The second I returned it for detail.”
“What happened after you returned it?”
I remembered.
Martin had come to my desk.
“This isn’t your lane.”
“It hit my cost center.”
“Approve it.”
“I need backup.”
He stared at me.
Then smiled.
“I’ll route it elsewhere.”
At the time, I thought he was annoyed.
Now I understood the invoice had probably gone to someone less curious.
The investigator asked, “Do you have that email?”
“Yes.”
Everything became evidence.
That night I stood at my bathroom mirror studying the ICD scar.
I thought about Martin’s face on the conference room video.
He had looked angry.
Not scared.
Not confused.
Angry.
At me.
For falling.
For interrupting the meeting.
For becoming a problem he could not manage.
The next morning Evelyn called.
“We found the revised presentation.”
“What revised presentation?”
“The one Martin saved after you sent your draft.”
I sat down.
“He removed the Northline slide?”
“Yes.”
“And the duplicated shipment values?”
“Yes.”
“Anything else?”
A pause.
“He added a closing slide.”
“What did it say?”
Evelyn’s voice became quiet.
“Operational variances are within expected tolerance. No material control concerns identified.”
I stared at the wall.
He had prepared to tell the room there was no problem.
Even while my source data showed four million dollars of one.
Then Evelyn added, “There’s metadata.”
“What metadata?”
“The slide was created at 9:42 Friday morning.”
Forty-two minutes before I collapsed.
Martin had not merely disagreed with my analysis.
He had already written the conclusion he wanted the room to believe.
May you like
And when my heart stopped in the middle of contradicting it, his first instinct had been the same as with the numbers.
Control the interpretation.